Are you considering a reverse mortgage? Explore our comprehensive guide to find the best reverse mortgage lenders of 2024. Discover what a reverse mortgage is, how it works, potential usage and more!
Are you a homeowner in or nearing retirement and facing concerns about maintaining your current lifestyle or managing unexpected expenses in your golden years? Fortunately, there are viable solutions to assist in effectively navigating these challenges.
One solution worth exploring is a reverse mortgage. This financial tool provides homeowners with the opportunity access the equity they have built up in their homes, all while avoiding the strain of having to make monthly mortgage payments.
In this extensive overview of the leading reverse mortgage lenders of 2024, we will discuss the key traits to consider when selecting a trustworthy reverse mortgage lender. We will also flesh out what reverse mortgages are, including how they work and their potential applications, so you can determine if they align with your financial goals.
We will also clear up several myths surrounding this unique financial product.
We have curated a list of the top reverse mortgage lenders by carefully evaluating various factors. These include their longevity in the industry, the range of products they offer, their availability across different states, how available their customer service is to their customers, as well as their ratings from the Better Business Bureau (BBB).
If we had to choose a single lender to recommend, our top pick for the Best Overall reverse mortgage provider is Mutual of Omaha Mortgage.
Mutual of Omaha Mortgage is our Best Overall Pick. Mutual of Omaha Mortgage is part of a trusted brand, it offers 24/7 availability to its customers, and has excellent customer service ratings.
Company History: Mutual of Omaha Mortgage
Mutual of Omaha Mortgage’s high ranking can be attributed to its affiliation with a reputable company that boasts a century-long history. Mutual of Omaha is a Fortune 300 company with its headquarters in Omaha, Nebraska, and is widely recognized for its diverse array of financial products.
Mutual of Omaha Mortgage says that it is committed to safeguarding its customers’ interests and assisting them in achieving their financial aspirations and a prosperous future.
Mutual of Omaha provides an extensive range of products, including life insurance, Medicare supplement insurance, disability insurance, traditional home mortgages, and reverse mortgages. Its wide breadth of products allows the company to meet the diverse needs of its clients.
With a team of experienced loan officers operating nationwide, Mutual of Omaha Mortgage maintains a strong reputation within the industry.
Reverse Mortgage Loan Options with Mutual of Omaha Mortgage
We appreciate that Mutual of Omaha Mortgage provides a diverse range of loan options. This gives customers greater confidence that they will find the right solution that will meet their needs. The reverse mortgage products offered by Mutual of Omaha mortgage include the following:
Home Equity Conversion Mortgage (HECM). The Home Equity Conversion Mortgage (HECM), commonly referred to as a reverse mortgage or HECM loan, is a federally backed loan only available to homeowners aged 62 or older. To be eligible, the home must serve as the homeowners’ primary residence and have accrued equity. With a reverse mortgage, borrowers have flexible options to receive funds: a single lump sum payment, regular monthly installments, a credit line, or a hybrid of these approaches. In 2023, the lending limit for HECM reverse mortgages set by the FHA exceeded $1 million for the first time.
HECM for Purchase. A Home Equity Conversion Mortgage for Purchase (HECM for Purchase) offers homeowners the opportunity to finance a portion of a new home purchase with a reverse mortgage along with a down payment from the proceeds of their previous residence. This unique arrangement enables qualifying homeowners to downsize or upsize during their retirement years, without the need for monthly mortgage payments.
Jumbo Reverse Mortgage. Mutual of Omaha Mortgage offers a proprietary reverse mortgage that offers borrowers the opportunity to access up to $4 million. This jumbo reverse mortgage option is for homeowners who wish to borrow amounts more than the FHA lending limit.
Reverse Mortgage Refinancing. Mutual of Omaha Mortgage also provides reverse mortgage refinancing options for homeowners who have already obtained a reverse mortgage. Reverse mortgage borrowers may consider refinancing their reverse mortgage for various reasons, including fluctuations in interest rates, an increase in home value, or adjustments to the FHA lending limit.
Traditional Mortgage Products. For those who are not eligible for a reverse mortgage loan, Mutual of Omaha also offers traditional conventional mortgage options.
Mutual of Omaha Reverse Mortgage Application Process: What to Expect
When working with Mutual of Omaha Mortgage to secure a reverse mortgage, you can expect the assistance of a committed loan officer who will guide you through every step of the process.
Below, you will find a summary of the reverse mortgage application process:
Step 1: Talk to a Reverse Mortgage Specialist
During this initial phase, a reverse mortgage specialist will assess detailspertaining to your property and personal financial circumstances to determine your eligibility for a reverse mortgage. The loan officer will provide you with an estimate of how much you may be able to receive and address any of your questions or concerns.
Step 2: Counseling
Before proceeding with a reverse mortgage application, it is mandatory for all potential applicants to complete a counseling session with a HUD approved counselor. Upon the completion of the counseling session, a certificate will be provided to you, which will need to be given to your reverse mortgage loan advisor before moving forward.
Step 3: File the Application
After completing the counseling session, you may submit your application. Your loan advisor will assist you with submitting your application and help you assemble the required documentation.
Step 4: Appraisal
Once your application is submitted, Mutual of Omaha Mortgage will request a professional home appraisal. In most cases, the appraisal will take about two weeks. During this time, the lender will also obtain other documentation such as a credit report, a title report, and other necessary documents.
Step 5: Underwriting
Upon submission of the application and associated documentation, a thorough review and processing will be conducted by underwriting. The underwriter will issue one of the following results: approval, approval with conditions, or denial. In the event that approval is granted with conditions, further documentation may be required, or home repairs may need to be completed for the loan to be finalized. Your reverse mortgage loan officer will reach out to you to address any outstanding requirements or repairs.
Step 6: Closing
Once the loan has been approved, Mutual will schedule the closing. You have the option to choose where you would like to sign the closing documents. It can happen at your home with the help of a mobile notary or at the office of the title company.
Step 7: Start Receiving Funds
After signing the closing documents, please be aware that a mandatory three-business-day waiting period before any funds can be received. The way you receive your funds depends on the method you selected during your application process.
Pros
Originates loans in 48 states and Washington, D.C.
Customer service available 24/7
Top customer ratings on third-party review websites
A+ Rating from the BBB
Mobile app
Free reverse mortgage calculator
Free reverse mortgage info guide
Pros
Not available in New York or West Virginia
Conclusion
Mutual of Omaha Reverse Mortgage is a subsidiary of a trusted brand with a long history. It offers a wide range of products to suit different needs, even if homeowners don’t meet the qualifications for a reverse mortgage. It has earned high customers ratings on external review platforms, and it has an A+ Rating from the BBB. In addition, it’s the only reverse mortgage lender we reviewed with 24/7 customer service and a mobile app.
Premier Reverse Mortgage — Good Option if You Live in New York
Overview
Premier Reverse Mortgage has a reputation for delivering personalized service, although its services are limited to a select number of states. It offers the following reverse mortgage loan options:
Home Equity Conversion Mortgages (HECM)
HECM for Purchase
Jumbo Reverse Mortgages
Furthermore, Premier has an informative website featuring comprehensive guides like the Reverse Mortgage Guide, Reverse Mortgage Purchase Guide, and a Reverse Mortgage Guide for Adult Children. These resources are designed to educate homeowners and their families.
It only offers reverse mortgages in 14 states and the District of Columbia, but one of those states is New York.
Premier has an A+ Rating from the Better Business Bureau.
Premier Reverse Mortgage Company History
Premier is based in Atlanta, Georgia and was founded in 2012 by industry veteran Matt Neumeyer, who possesses extensive experience in reverse mortgages. Premier says that it is focused on serving its customers with integrity and personal service.
Pros
A+ Rating from the BBB
Free informational guides
Available in New York
HECM for Purchase Calculator
Spanish version of website
Cons
Only available in 14 states and the District of Columbia
No reverse mortgage calculator (only HECM for purchase)
GoodLife Home Loans — Good Option if you live in West Virginia
Overview
GoodLife Home Loans is a relatively new reverse mortgage lender, only opening its doors in 2018. It currently offers the following reverse mortgage loan options:
HECM Reverse Mortgage Loans
Jumbo Reverse Mortgages
Reverse Mortgage Financing
In its short life, it has received an A+ Rating from the Better Business Bureau and has top customer service ratings on third-party review websites, such as Trustpilot.
It only offers reverse mortgages in 38 states, but one of those states is West Virginia.
GoodLife Home Loans Company History
GoodLife Home Loans is affiliated with Traditional Mortgage Acceptance Corporation.
Traditional Mortgage opened in 2012. It purchases reverse mortgages as a secondary market purchaser, and it’s a Ginnie Mae issuer of mortgage-backed securities (MBS). Once it purchases closed reverse mortgage loans from other lenders, it pools them together, and issues them as a Ginnie Mae Security. It is also a wholesale underwriter for reverse mortgages.
GoodLife Home Loans opened as a reverse mortgage lender in 2018. The company says that it is committed to making reverse mortgages more accessible.
GoodLife has corporate offices in Bellevue, Washington and Mission Viejo, California.
Pros
A+ Rating from the Better Business Bureau (BBB)
High customer review ratings on third-party websites
Available in West Virginia
Free Reverse Mortgage Calculator
Cons
Only available in 38 states
Does not offer HECM for Purchase
A Comprehensive Overview of Reverse Mortgages
Reverse mortgages have gained significant popularity among homeowners approaching or already in retirement. Revere mortgages offer older homeowners an added financial resource to address a range of expenses, including medical bills, home renovations, and unforeseen costs.
As individuals often find a significant portion of their net worth tied up in their homes, it is not uncommon for them to explore options to access this wealth. The U.S. Department of Housing and Urban Development (HUD) estimates that home equity accounts for about two-thirds of an average retiree’s total wealth.
To address this, many seniors are turning to reverse mortgages. Unlike Home Equity Loans or Home Equity Lines of Credit (HELOCs), reverse mortgages offer a unique solution as a tool that allows homeowners to access the capital in their homes but without requiring monthly mortgage payments to pay it back.
This comprehensive guide will cover what you need to know about reverse mortgages so that you can make an informed decision.
What is a Reverse Mortgage?
Reverse mortgages are a financial tool that gives older homeowners the opportunity to access their home’s equity and continue to reside in their home, without the obligation of monthly mortgage payments. They offer a path for accessing additional funds while still maintaining ownership of your home.
The HECM (home equity conversion mortgage), commonly referred to as a reverse mortgage, continues to be the top choice for homeowners seeking a reverse mortgage loan. Reverse mortgages are overseen by the U.S. Department of Housing and Urban Development (HUD) and insured the Federal Housing Administration (FHA).
A reverse mortgage is a loan taken out against the equity in the home, like a home equity loan or a home equity line of credit (HELOC). Unlike a traditional mortgage, it permits homeowners to borrow against their property’s accumulated value.
A reverse mortgage provides unique advantages to eligible homeowners as it eliminates the need for monthly mortgage payments for repayment, setting it apart from other available options.
This is one way that a reverse mortgage can help free up cash, since the mortgage is typically most Americans’ largest expense.
Homeowners with a reverse] mortgage are still obligated to paying the property taxes, homeowner’s insurance, home maintenance expenses, and other fees, where applicable.
A reverse mortgage is repaid under several conditions: when the property is sold, when it is no longer the primary residence, if homeowners do not fulfill loan obligations, or upon the homeowner’s passing.
How Does a Reverse Mortgage Loan Work?
When securing a reverse mortgage loan, it initially pays off your existing traditional mortgage.
To access the remaining equity, there are several options available for receiving your funds, including a lump sum payout, fixed monthly installments, a credit line, or a mixture of these options.
The choice you make will be determined by your specific financial situation.
Those who are a good fit for the lump sum payment method include those planning major projects like home renovations or debt repayment. Those who may be a good fit for choosing monthly payments are those who are seeking to help cover their monthly expenses. Lastly, the line of credit provides flexibility and additional funds for unexpected expenses or personal use.
Reverse mortgage borrowers enjoy significant flexibility as there are no restrictions on how they can use the funds.
When selecting monthly payments as the preferred method to receive funds, individuals have the choice between term monthly payments, which are paid out for a set number of months, or tenure monthly payments that are paid out if the borrower resides in the home and satisfies the reverse mortgage obligations.
The Factors That Determine Your Reverse Mortgage Loan Amount
There are three key factors that play a role in determining your reverse mortgage loan amount: your age, the interest rates, and your home’s value.
It’s also important to consider other factors, such as the lending limit set by the FHA, and the method of fund disbursement you choose.
The FHA sets a limit on the total loan amount homeowners can receive from HECM reverse mortgages. In 2023, the FHA lending limit surpassed $1 million.
When opting for a lump sum payment, keep in mind that there is a rule that limits the amount you can receive called the principal limit rule.
Under the principal limit rule, you can only access 60 percent of the approved loan amount within the initial year of the reverse mortgage loan.
To address this, borrowers can combine a lump sum with monthly installments or credit line.
It’s worth noting that choosing a lump sum comes with the advantage of a fixed interest rate.
Both the monthly installments and credit line methods have adjustable interest rates. However, interest is only charged on the funds they actually receive.
One benefit of going with the line of credit payment option is that the remaining balance has the potential to grow over time. It’s important to note that the principal limit rule also applies to the line of credit option.
Use a reverse mortgage calculator to obtain a more precise estimate of your potential loan amount.
When considering a reverse mortgage, it’s important to note that there are distinct requirements that set it apart from other mortgage and home equity loan options. If you’re considering applying for a reverse mortgage, here are the qualifications you need to meet:
At least one borrower must be a minimum of 62 years old.
The property must be the homeowners’ primary residence. Keep in mind that secondary residences or vacation homes are not eligible for this type of mortgage.
The home needs to be in good condition.
The home should have accumulated some equity.
The property must fall into one of the following categories: a multi-family property with no more than four units in which the homeowners reside in one unit, a single-family home, a condominium that meets certain criteria, or an approved manufactured home.
Prospective borrowers are required to participate in a comprehensive counseling session with a third-party counseling service approved by HUD prior to applying for a reverse mortgage.
Homeowners with a reverse mortgage are obligated to occupy the property as their primary residence. They must also stay current on property taxes, homeowner’s insurance, and maintain the home.
What are the Types of Reverse Mortgages?
Reverse mortgages come in four distinct types, each serving its own specific purpose, including the following:
HECM Reverse Mortgage
A home equity conversion mortgage (HECM) is the most used type of reverse mortgage. Homeowners aged 62 or older, who live in their primary residence and have equity in their home, are eligible for a reverse mortgage. These mortgages are backed by the federal government through HUD and the FHA. They are also subject to the FHA borrowing limit.
HECM for Purchase
A Home Equity Conversion Mortgage for Purchase (HECM for Purchase) enables homeowners to finance part of their new home using a reverse mortgage. This approach combines the reverse mortgage with a substantial down payment that is typically taken from the sale of their previous home. This allows older homeowners a way to downsize or upgrade their homes in retirement without the need for monthly payments.
Jumbo Reverse Mortgage
Jumbo reverse mortgage loans are specifically designed for eligible homeowners who wish to access funds exceeding the lending limit set by the FHA. These loans are created by individual lenders and can go up to $4 million. While they may have higher interest rates than traditional options, borrowers are not required to pay for mortgage insurance premiums.
Single-Purpose Reverse Mortgage
Single-purpose reverse mortgages are a less common type of reverse mortgage that is specifically designed for homeowners who are at least 62 years old. Lenders typically authorize these programs for specific purposes, often limited to home renovations. They are primarily attained through non-profit groups and state and local governments.
What are the Costs and Fees Associated with a Reverse Mortgage?
Reverse mortgages are accompanied by a range of costs and fees you will want to take into account.
Here is a breakdown of the fees that you may pay when acquiring a reverse mortgage. Keep in mind that some of these fees can be included in the loan itself:
The HUD-mandated counseling session typically costs between $125 to $200. However, as per the Consumer Financial Protection Bureau (CFPB), for those who cannot afford this fee, the counseling agency is not allowed to charge you, and it should provide a detailed explanation of all charges before the counseling session.
The origination fee is charged by the lender, but the CFPB says that it cannot exceed $6,000. This fee varies from lender to lender.
Closing costs are made up of numerous fees that are charged in the application process, which typically include credit checks, home inspection fees, title search fees, and appraisal fees.
When you originate a loan, the lender will levy the first mortgage insurance premium. This premium goes to the FHA and serves as insurance that you’ll receive the promised funds, the CFPB says.
These are the ongoing expenses you can anticipate paying after you close on your loan:
When it comes to interest rates for reverse mortgages, you have two options: a fixed rate or an adjustable rate. If you opt for a lump sum payout, you’ll enjoy the stability of a fixed interest rate. However, if you choose any other method, you’ll have an adjustable rate. Interest is only applied to the funds that have been disbursed.
Annually, you will pay a mortgage insurance premium, which is calculated at 0.5 percent of your remaining mortgage balance.
When you secure a loan, it is common for the lender to impose a servicing fee to cover the costs of managing your loan.
Homeowners are responsible for paying property taxes, homeowner’s insurance, and other obligatory fees that may apply.
When Does it Make Sense to Get a Reverse Mortgage?
Reverse mortgages are no longer considered a last-ditch option for retired homeowners in need of extra cash. In recent years, the perception of reverse mortgages has evolved significantly.
Reverse mortgages have gained recognition as a viable solution to address various needs and situations. These may encompass, but are not limited to, the following scenarios:
If you need additional income to cover your monthly expenses. Homeowners seeking to supplement their income may explore additional avenues if they find that their Social Security benefits and other sources of income fall short of their monthly expenses.
If you want to remain in your home. A reverse mortgage offers a convenient option for individuals approaching retirement to comfortably age in their own homes. Despite the availability of retirement communities in popular states like Florida and Arizona, research from the Center for Retirement Research reveals that most retired Americans choose to stay in the same houses they occupied from their early 50s onward.
If you need additional savings. A Federal Reserve study reported that a large share of Americans has inadequate savings for retirement. If you’re facing financial challenges and looking for ways to manage costs, a reverse mortgage could potentially offer a viable solution.
If the market is in a downturn. The stock market is known for its fluctuations, impacting various investments like 401(k)s and IRAs. In the event of a market downturn during retirement, individuals can use a reverse mortgage to supplement their income until the market recovers and they feel comfortable withdrawing their investments.
If you want to postpone Social Security benefits. Postponing claiming Social Security benefits leads to a gradual increase in the amount received by retirees. For those homeowners who need additional income until they are ready to start collecting their benefits, a viable option is a reverse mortgage. Homeowners have the flexibility to delay Social Security benefits until reaching the age of 70, while they qualify to secure a reverse mortgage starting from the age of 62.
What are the Reverse Mortgage Protections?
Reverse mortgages garnered negative attention in the past, leaving homeowners concerned about the safety of this product. However, the federal government has taken measures to address these risks by implementing new laws and stronger safeguards.
As a result, homeowners can have greater confidence in pursuing this type of loan. Here are some of the protections that have been instituted:
Cross-selling ban. The Justice Department reported in 2021 that elder fraud cost Americans aged 60 and older $1.7 billion. To protect older homeowners, the federal government has prohibited cross-selling reverse mortgages with other financial products. This measure aims to prevent scammers from persuading homeowners to invest reverse mortgage proceeds in other financial or insurance products. While there are no limitations on how reverse mortgage funds are utilized, it is important to be aware that it is illegal for someone to encourage you to obtain a reverse mortgage for the purpose of purchasing another product from them.
Non-recourse loan protections. Reverse mortgages are repaid if the homeowners sell the home, no longer live in it as their primary residence, or pass away. If the final loan amount exceeds the home’s value, the borrowers or their heirs are not obligated to pay the difference. This is because reverse mortgages are “non-recourse loans” and the lender cannot use any other assets besides the home to settle the loan. Mortgage insurance premiums ensure this protection.
Right to Cancel. When applying for a reverse mortgage, it’s important to know that you have the right to cancel the loan at any time during the application process. You can also cancel the loan within three business days of signing the loan documents.
What You Should Know About Reverse Mortgage Scams
A reverse mortgage is a valid financial product that offers several potential benefits. However, it is important to be cautious of individuals who may attempt to exploit potential reverse mortgage borrowers through fraudulent schemes.
Here are some reverse mortgage scams to be aware of:
Beware of contractors who aggressively promote reverse mortgages to finance home repairs or renovations.
Beware of individuals posing as Department of Veterans Affairs (VA) employees. The VA does not offer reverse mortgages. While it’s not uncommon for lenders to provide military discounts, this doesn’t mean that the VA has any affiliation with reverse mortgages.
Beware of loan officers who try to coerce you into a reverse mortgage through scare tactics. Reputable reverse mortgage brokers serve as valuable resources, offering comprehensive information and addressing inquiries pertaining to HECM loans. Brokers should never exert undue pressure on homeowners to take out the loan or try to influence how the funds are used.
A common misconception surrounding reverse mortgages is that homeowners transfer ownership of their homes to lenders, who then compensate them for it.
A reverse mortgage is simply a loan acquired against the equity in the home, which is repaid when the home is sold, the last remaining borrower passes away, or the home is no longer the primary residence.
Like a conventional mortgage, the borrower retains the title and ownership of the home, with the obligation to repay the loan when the time comes.
> What Happens to a Reverse Mortgage When a Homeowner Passes Away?
When a homeowner with a reverse mortgage passes away, the surviving spouse may continue living in the home if they are a co-borrower on the loan. If the surviving spouse is not listed as a borrower, there are still options available for them to remain in the property, subject to specific conditions.
In the event of the last borrower’s death, the lender will send a notice that the loan is due and payable. Heirs then have the option to sell the home, keep the home by paying the loan balance, sign the title over to the lender, or do nothing and let the bank takeover.
> Will My Family Lose Their Inheritance?
You can still leave your home to your children or heirs. Your heirs can choose to keep the home by paying off the reverse mortgage or selling it.
The loan is a “non-recourse” loan, meaning your heirs will never owe more than the loan value or 95% of the appraised value.
In addition, no other assets are tied up in a reverse mortgage, so any other investments, assets, and savings are not at risk.
It is recommended to involve your family in the process so they can know what to expect and plan accordingly.
> Can You Get a Reverse Mortgage with Bad Credit?
There is no specific credit score requirement needed to obtain a reverse mortgage. That being said, lenderstake credit scores and credit history into account as part of their financial assessment.
This assessment helps them evaluate whether applicants can meet the financial obligations of the loan as reverse mortgage borrowers must be able to continue to pay the property taxes, home insurance, and home maintenance costs.
It’s worth noting that even applicants with bad credit may still be approved if they can demonstrate their ability to meet the necessary obligations.
> How Long Does the Reverse Mortgage Application Process Take?
Securing a reverse mortgage loan is a comprehensive and meticulous process. It typically takes approximately 45 days from initiation until the disbursement of funds begins.
Methodology
This evaluation of the best reverse mortgage companies incorporates the following criteria in evaluating each company: business longevity, reverse mortgage product offerings, customer ratings on third-party review websites, ratings from the Better Business Bureau (BBB), state licensing footprint, and the availability of a mobile app.
Most homeowners want two things before they commit to a remodel: a realistic sense of cost and a clear picture of what the finished space will look like. Milan Design + Build helps deliver both through its online remodeling estimator and personalized design consultations, supported by a showroom experience and 3D renderings.
“The online estimate gives homeowners a starting number in about a minute, and the showroom and 3D renderings let them see materials and layouts before anything is built,” says David Noriani, CEO of Milan Design + Build. “Keeping design, permits, and construction with one team helps us manage expectations and keep everyone working toward the same vision.”
Courtesy of Milan Design
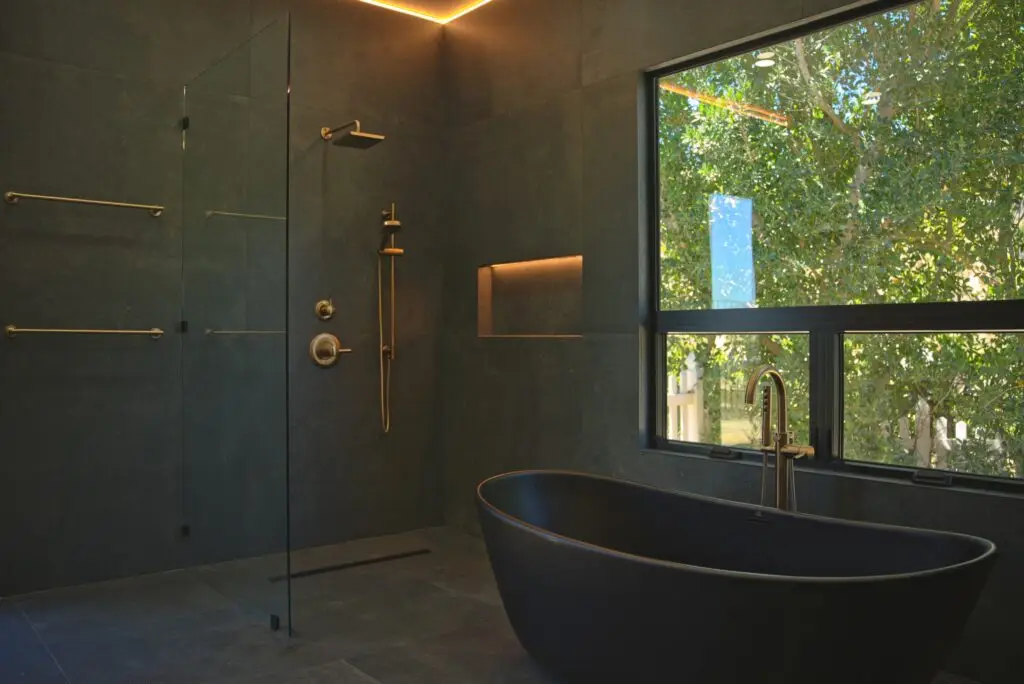
Modern design is a particular focus for Milan, with an emphasis on clean lines, natural light, functional layouts, and carefully selected materials. The team adapts each design to the homeowner’s lifestyle and the character of the property. Milan Design + Build combines thoughtful design with construction expertise, creating spaces that are as functional as they are beautiful.
The online estimator covers kitchen remodels, bathroom renovations, full-home remodels, and ADU construction. At Milan’s showroom on Carroll Road, visitors can review real materials, finishes, and design options, meet the design-build team, and discuss project scope, budget, and timing. Consultations can also be held virtually for homeowners who prefer to start remotely.
At Milan Design + Build, one integrated team works on the entire project. Design and construction aren’t divided between separate firms. The process begins with a consultation and feasibility review, followed by design, space planning, and 3D renderings developed from detailed measurements and digital scans. The team also coordinates architectural plans, structural engineering, city approvals, and material selection, with construction overseen by a dedicated project manager.
Homeowners can explore their remodeling options, get an initial estimate, or request a design consultation at MilanBuild.com.
Philanthropists and Scientists Join Forces for a Bold $55 Million Campaign
La Jolla Institute for Immunology (LJI) is going public with a bold bet: a $55 million campaign to propel medical research into a new era. The Campaign for LJI will fuel discovery, empower scientific innovation, and expand the impact of immunology on human health.
The Institute quietly kicked things off in 2023, guided by its Board, campaign volunteers, and early believers. Nearly 80% of the $55 million goal is already in hand. Now LJI is opening the doors and inviting the whole community to carry their visions across the finish line and back discoveries that change how LJI researchers understand, treat, and prevent disease.
And there’s a bonus. To mark the public launch, LJI Board member and Campaign Honorary Chair Anthony R. Carr is offering a special matching gift so new donors can double their impact. Full details are here.
The Promise of Immunology
Immunology has already rewritten human history. Advances in immune science helped wipe out smallpox, pushed polio to the brink of elimination, and revolutionized how we prevent and treat infectious disease. Today, immune-based therapies are opening doors for patients with cancer, autoimmune disorders, and other serious illnesses once considered untreatable.
For nearly four decades, LJI scientists have stood on the front lines, driven by one insight: the immune system shapes disease in virtually every organ in the body. By decoding how the immune system works and how to harness it to prevent and treat disease, LJI researchers are chasing the Institute’s ultimate mission: Life Without Disease®.
To make that mission real, the Institute pairs world-class scientists with cutting-edge technology, speeding up breakthroughs and turning discoveries into transformative new therapies that ease suffering worldwide.
The Campaign for LJI supercharges that momentum, uniting the vision of the Institute’s scientists with a community that believes in research. Focused on advancing LJI’s most promising areas of study, the campaign aims to help build a future free from the burden of disease, a goal that demands bold ideas, lasting partnerships, and generous philanthropic support.
The Campaign for LJI will advance research across three critical pillars:
1. President’s Priority Fund. Flexible, unrestricted dollars let big ideas move now, not later. Scientists can launch high-risk, high-reward projects, bring experts together across disciplines, build transformative technologies, and train tomorrow’s scientific leaders.
2. Center for Sex-Based Differences in the Immune System. Male and female immune systems don’t respond the same way, and LJI researchers are tracing the fundamental differences down to individual cells and molecular pathways. The Campaign will speed up this pioneering work, revealing hidden drivers of disease and paving the way for more precise, biologically informed therapies for autoimmune disorders, infectious diseases, cancer, and beyond.
3. Center for Vaccine Innovation. Immunologists, bioengineers, and vaccine experts are teaming up to design the next generation of vaccines and immune-based therapies. With donor support, LJI scientists can engineer longer-lasting and more personalized vaccines, pinpoint the cellular mechanisms driving protective immunity, and refine delivery methods to prevent autoimmune disease and treat cancer.
A Lasting Impact
As the campaign enters its public phase, LJI welcomes new partners and supporters to join this landmark initiative. Community support is essential to accelerating scientific discovery, and there are many meaningful ways to help shape the future of immunology. Donors may direct their gifts to any campaign priority or other area of interest. As a comprehensive campaign, all gifts to LJI count toward the campaign goal, regardless of designation. Join the campaign, and multiply your impact with our limited-time matching opportunity.
Shiley Center for Orthopaedic Research and Education at Scripps Clinic recently received a $12.7 million grant from the California Institute for Regenerative Medicine to investigate whether they can transform stem cells into tissue that can repair some types of knee injuries. Currently, if a patient has lost most, if not all, of the cartilage in their knee, then their doctor will recommend a total joint replacement. Joint replacement is safe and effective, but patients who’ve only lost part of their cartilage often don’t qualify. A stem cell-based treatment would provide these patients an option that doesn’t involve donor tissue. Click here for more on the preclinical trial process.
For more nutrition, wellness, and healthy living tips, sign up for the San Diego Health newsletter here.
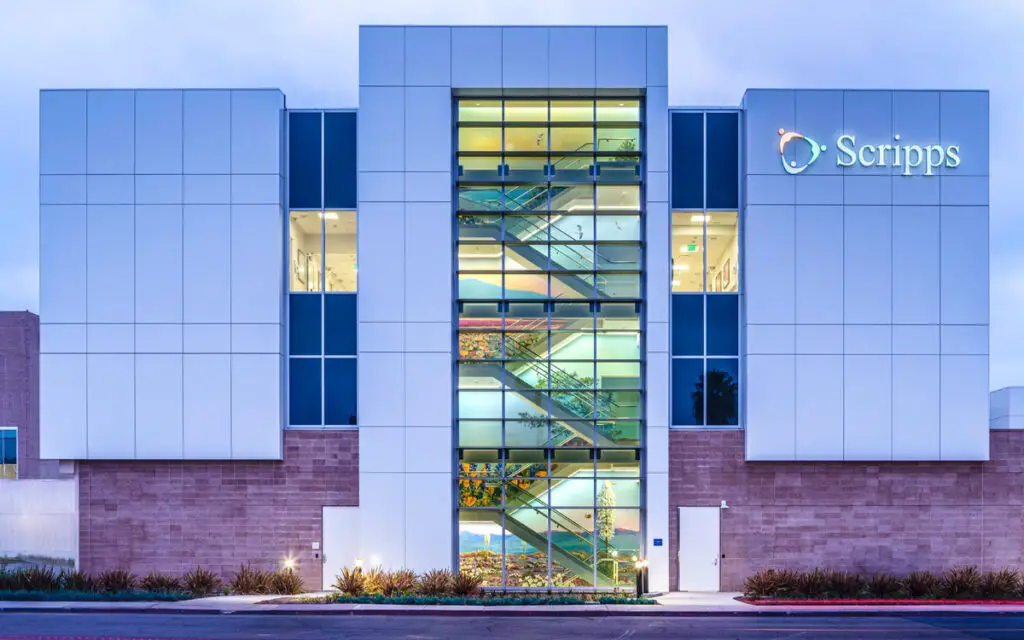
The recently opened Lusardi Tower at Scripps Memorial Hospital Encinitas is a state-of-the-art addition to the hospital staffed by dedicated team members who’ve helped make Scripps one of the nation’s leading healthcare systems. Complementary to that medical excellence, the Lusardi Tower also represents the latest expansion of the Scripps Arts for Healing Program. The philanthropic initiative strategically places nature- and community-based artwork throughout the hospital to support health and well-being. Both Scripps Encinitas and Scripps Memorial Hospital La Jolla have healing arts programs as part of new building projects and growth on the campuses. Click here to read more about the Healing Arts Program and how residents from a nearby retirement community showed their support.
For more nutrition, wellness, and healthy living tips, sign up for the San Diego Health newsletter here.
From century-old Craftsman homes to vegan fantasy bars, dive bars, and a tiki room built for exactly two people, this is one of San Diego’s great little neighborhoods
You may not realize it, but Balboa Park is bigger than Central Park (in fact, 1.5 times larger). Pressed right up against its southeastern edge is a little architecture farm built on old trolley bones, where houses look like someone was collecting architectural styles and local businesses are still run by people who seem personally invested in keeping this place interesting.
This is South Park.
To understand why it feels the way it does today—less like one commercial strip and more like a handful of tiny villages—you have to go back to the trolley.
How the Trolley Built South Park
The land that became the original South Park Addition (the subdivision’s original name) was surveyed in 1870 and officially filed in 1890, but the neighborhood really started becoming a neighborhood in the early 1900s. The Bartlett Estate Company began developing and marketing the tract in earnest around 1906, pairing lots and new homes with something extremely useful if you lived outside Downtown in the horse-and-buggy era: an electric streetcar.
On May 1, 1906, the South Park and East Side Railway made its first trip. Developers didn’t just build near transportation; they helped pay for the transportation, then used it to sell the dream. Downtown had industry, noise, and congestion. Out here were palms, sidewalks, utilities, room to breathe and a four-cent ride back to the city.
It worked. Homes began filling in around the streetcar route, and little commercial clusters grew around the places where people got on and off. That transportation pattern is still written into South Park’s geography. Some of the neighborhood’s odd street geometry is also due in part to the trolley—the old line cut across parcels instead of politely obeying the grid, leaving behind pieces of land that later businesses learned to build around. Places like Station Tavern sit on the former easement and station site of San Diego’s No. 2 trolley line.
Then San Diego went big for the 1915 Panama-California Exposition in neighboring Balboa Park. The exposition transformed much of the park and helped push the city through another burst of building and growth. South Park was right there to absorb some of that momentum.
And the people building houses here had taste.
Walk the residential streets now and it can feel like somebody planted an architectural sample garden: Craftsman, Prairie, Mission Revival, Tudor Revival, Spanish Colonial Revival. Creedence Clearwater Revival. All the revivals. The neighborhood includes work by Irving Gill, one of the defining architects of early modern California; Gill-designed Prairie homes still stand along Granada Avenue.
The city formally designated the South Park Historic District in 2017, recognizing roughly 400 properties and a period of significance stretching from 1906 through 1949. In other words, a lot of what makes the place feel old is actually old.
While the trolley eventually disappeared, the basic idea behind it didn’t. South Park is still a neighborhood organized around little pockets of human activity: a couple blocks where you can buy a record, drink a beer, find a 60-year-old lamp, eat a vegan burger beneath gothic beasts, browse a bookstore, and walk home past a century-old Craftsman.
The 30th-and-Fern area may be the clearest example. Several surviving buildings there date to South Park’s early development, including the old Fire Station No. 9, Rose Grocery building, and Burlingame Garage. What began as infrastructure for a young streetcar suburb became the neighborhood’s commercial heart.
That history is also partly why buying a house here can be competitive. There isn’t some endless supply of vacant land waiting around the corner for another subdivision. Much of the neighborhood filled in generations ago, and the architecture itself is part of the appeal.
San Diego Mag’s been documenting the city for 78 years. And we’ve been looking for a partner who loved the city enough to help us tell its stories. Redfin is that partner. They’re helping us tell the story of some of the city’s most unique neighborhoods. They launched Redfin Early Access this year to get their people in first and to see certain coming-soon and exclusive listings on Redfin before they appear on other major real-estate sites.
First up: South Park.
Here are some of the people and places worth knowing here:
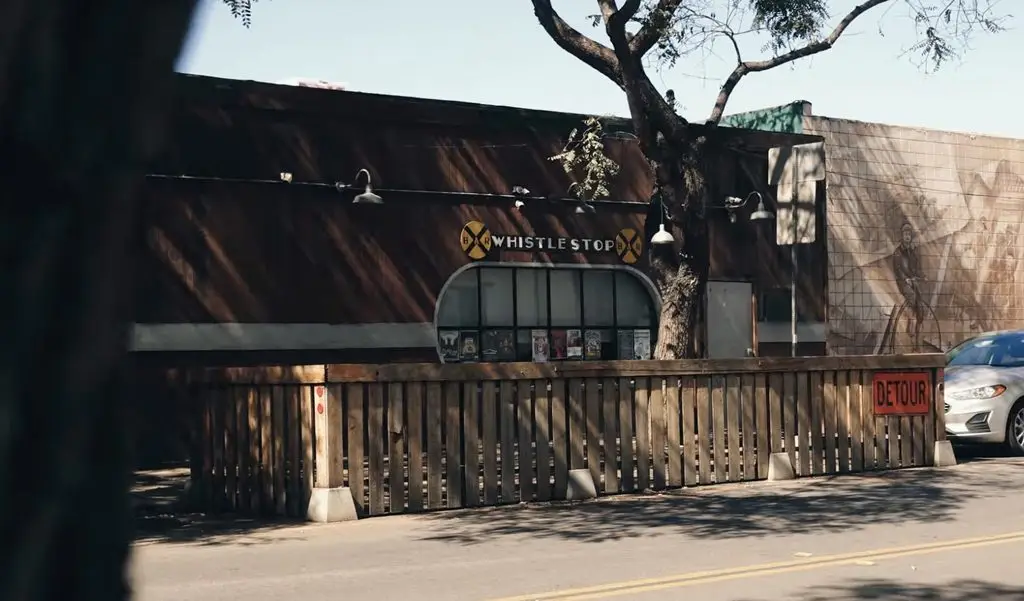
Whistle Stop Bar
Big Kitchen Cafe
Start with Judy “the Beauty” Forman, because it’s difficult to explain South Park without her. The former social worker bought Big Kitchen in 1980 and turned a neighborhood breakfast joint into a gathering place for artists, musicians, activists, politicians, eccentrics, and pretty much anyone who needed somewhere to belong. As Judy puts it, “I built this for people who others passed over.”
One of those people was a young single mom named Whoopi Goldberg, who worked as a dishwasher here before the WhoopiGoldberg part of her career happened. Today Big Kitchen still serves breakfast and lunch Thursday through Monday.
3003 Grape Street
Whistle Stop Bar
Whistle Stop reopened in 2001, right as South Park’s little independent-business ecosystem was finding a new generation. Owner Sam Chammas—also connected to Live Wire and, later, Station Tavern—helped turn it into the kind of neighborhood bar where the calendar can jump from a DJ night to live bands to some strange communal event nobody at a normal sports bar would propose.
The room still has that laid-back, slightly sweaty house-party quality. Check what’s happening before you go, because Whistle Stop changes personality depending on the night: sometimes neighborhood beer, sometimes everyone dancing beneath the disco ball like work tomorrow was canceled.
2236 Fern Street
Station Tavern
Station Tavern may be the most literal example of old South Park becoming new South Park. It opened in 2009 on land once crossed diagonally by the No. 2 trolley line, and architect Lloyd Russell incorporated that history into the design rather than pretending the weirdly shaped lot wasn’t weirdly shaped. The project won the San Diego Architectural Foundation’s Grand Orchid Award the same year it opened.
Sam Chammas built the place as an open-air burger-and-beer spot with big communal tables, a backyard, room for kids, and room for dogs. It still works exactly that way: get a burger, get the tots, let everybody spread out, stay awhile.
2204 Fern Street
Kindred + Throne Room
Kindred arrived in late 2015 looking nothing like the beige-and-leafy vegan restaurant stereotype. The place went full gothic fever dream—heavy music, wild cocktails, decadent plant-based food—and eventually collected national vegan accolades plus local Restaurant of the Year and design honors.
And in 2026, it got even weirder. Hidden behind a chain-mail passage inside Kindred is Throne Room, a medieval-fantasy cocktail chamber whose mythology grew out of a Dungeons & Dragons-inspired map the Kindred team created for a 2017 Coachella pop-up. The 90-minute experience has scroll menus, plant-based mezze, cocktails and zero interest in pretending restaurants need to behave normally.
1503 30th Street
Bad Madge & Co.
Vinyl Junkies Record Shack
Vinyl Junkies has good music-scene DNA. Founder Eric Howarth previously ran indie label Hi-Speed Soul, whose roster included acts like Nada Surf and Swervedriver, then teamed with Casbah owner Tim Mays after the pair had spent years putting on Vinyl Junkies record swaps.
They opened the South Park brick-and-mortar shop in 2017, and it remains a buy-sell-trade temple for people who understand that owning music on a physical object is irrational in exactly the right way. Go flip through the new arrivals. Leave holding something you had absolutely no intention of buying.
2235 Fern Street
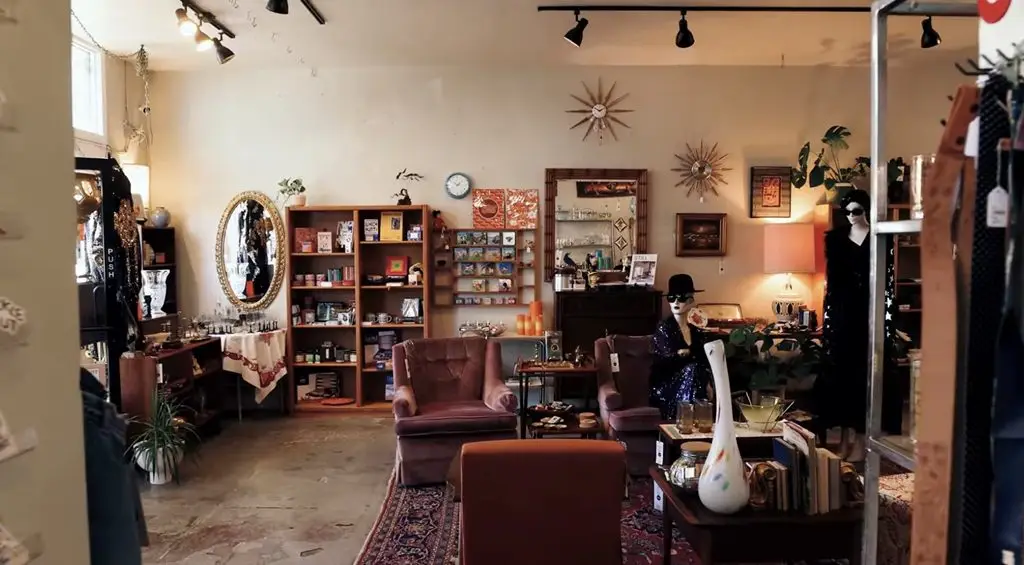
Bad Madge & Co.
Bad Madge is what happens when “vintage store” doesn’t quite explain the situation. Owner Tanya McAnear and her team fill the shop with furniture, clothing, barware, records, art, jewelry, collectibles, and various objects that seem like they may know things about their previous owners. The shop opened in 2011 and has made reuse and upcycling part of its identity ever since. Go in without looking for anything specific—specificity will only slow you down.
2205 Fern Street
Thread + Seed
Across the neighborhood’s vintage-and-vinyl universe sits Thread + Seed, a local boutique built around clothing, denim, gifts, and personal styling. Its South Park shop has an especially deep denim program—petite, tall, wide-leg, straight, flare—and the store also offers one-on-one styling built around color and body type. In other words, this is where you go after deciding the jeans currently on your body have betrayed you. South Park understands that sometimes personal renewal begins with pants.
2220 Fern Street
The Book Catapult
Seth Marko started The Book Catapult as a book blog in 2006. In 2017, he and his wife, Jennifer Powell, turned it into an actual bookstore in South Park, specializing loosely in fiction, local interest, and children’s books while maintaining the more important bookseller skill: putting something into your hands that you didn’t know you needed.
There are staff picks, author events, signed books, and the dangerous possibility of walking in for one title and emerging with four. Because no one ever died thinking, “I shoulda read less.”
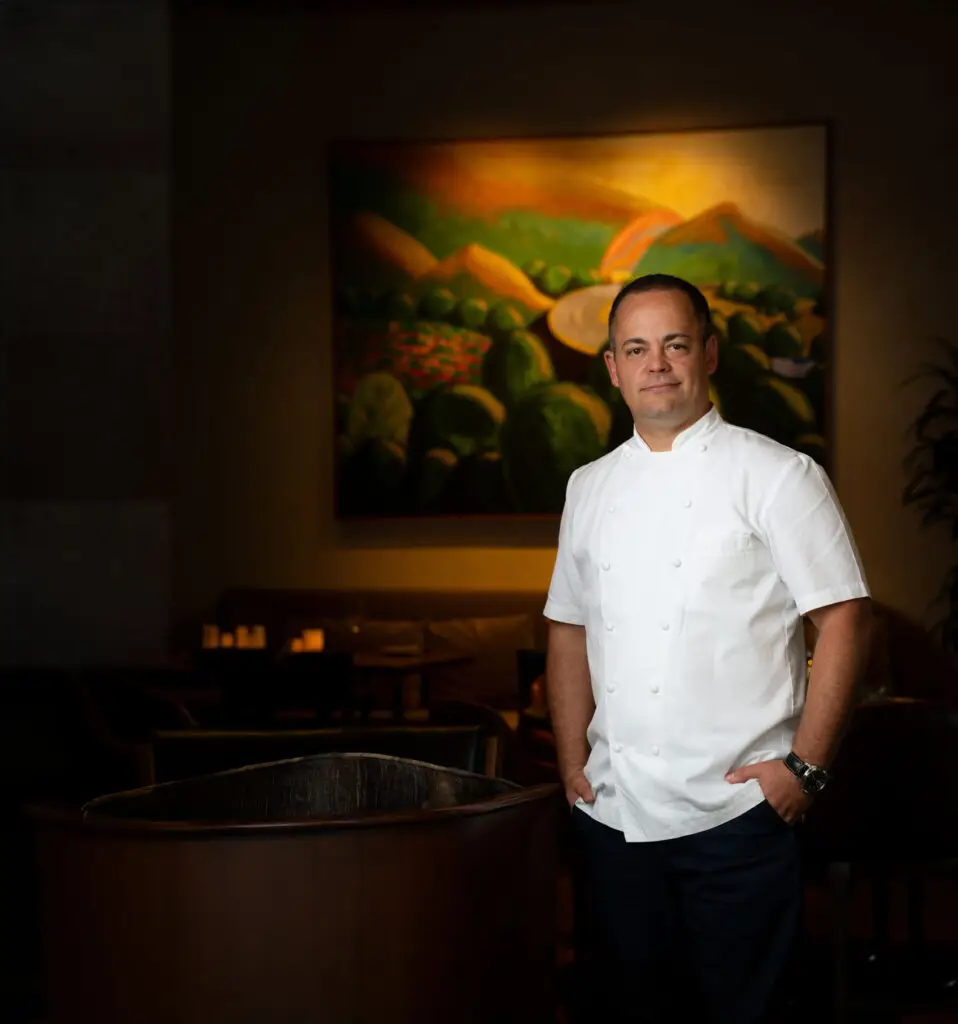
Chef Roberto Alcocer showcases all that Mexican cuisine and culture has to offer at Oceanside’s Valle. The Michelin-guide recommended restaurant takes inspiration and techniques from all over Mexico—with a heavy Baja influence—and blends them with local San Diego ingredients to create original and delectable contemporary Mexican cuisine. The seasonal tasting menu allows Chef Alcocer to experiment with the freshest available ingredients, creating dishes that defy guests’ expectations, while the wine list features more than 100 labels from Mexican artisans. Even the restaurant’s walls are a celebration of Mexican culture, all decorated with work from artists of Baja.
“My favorite part of being a chef of Valle is being able to showcase the Mexico that I know to everyone who visits,” Chef Alococer says. “Not only through the food, but with the design, culture, and welcoming service.”
Try This!
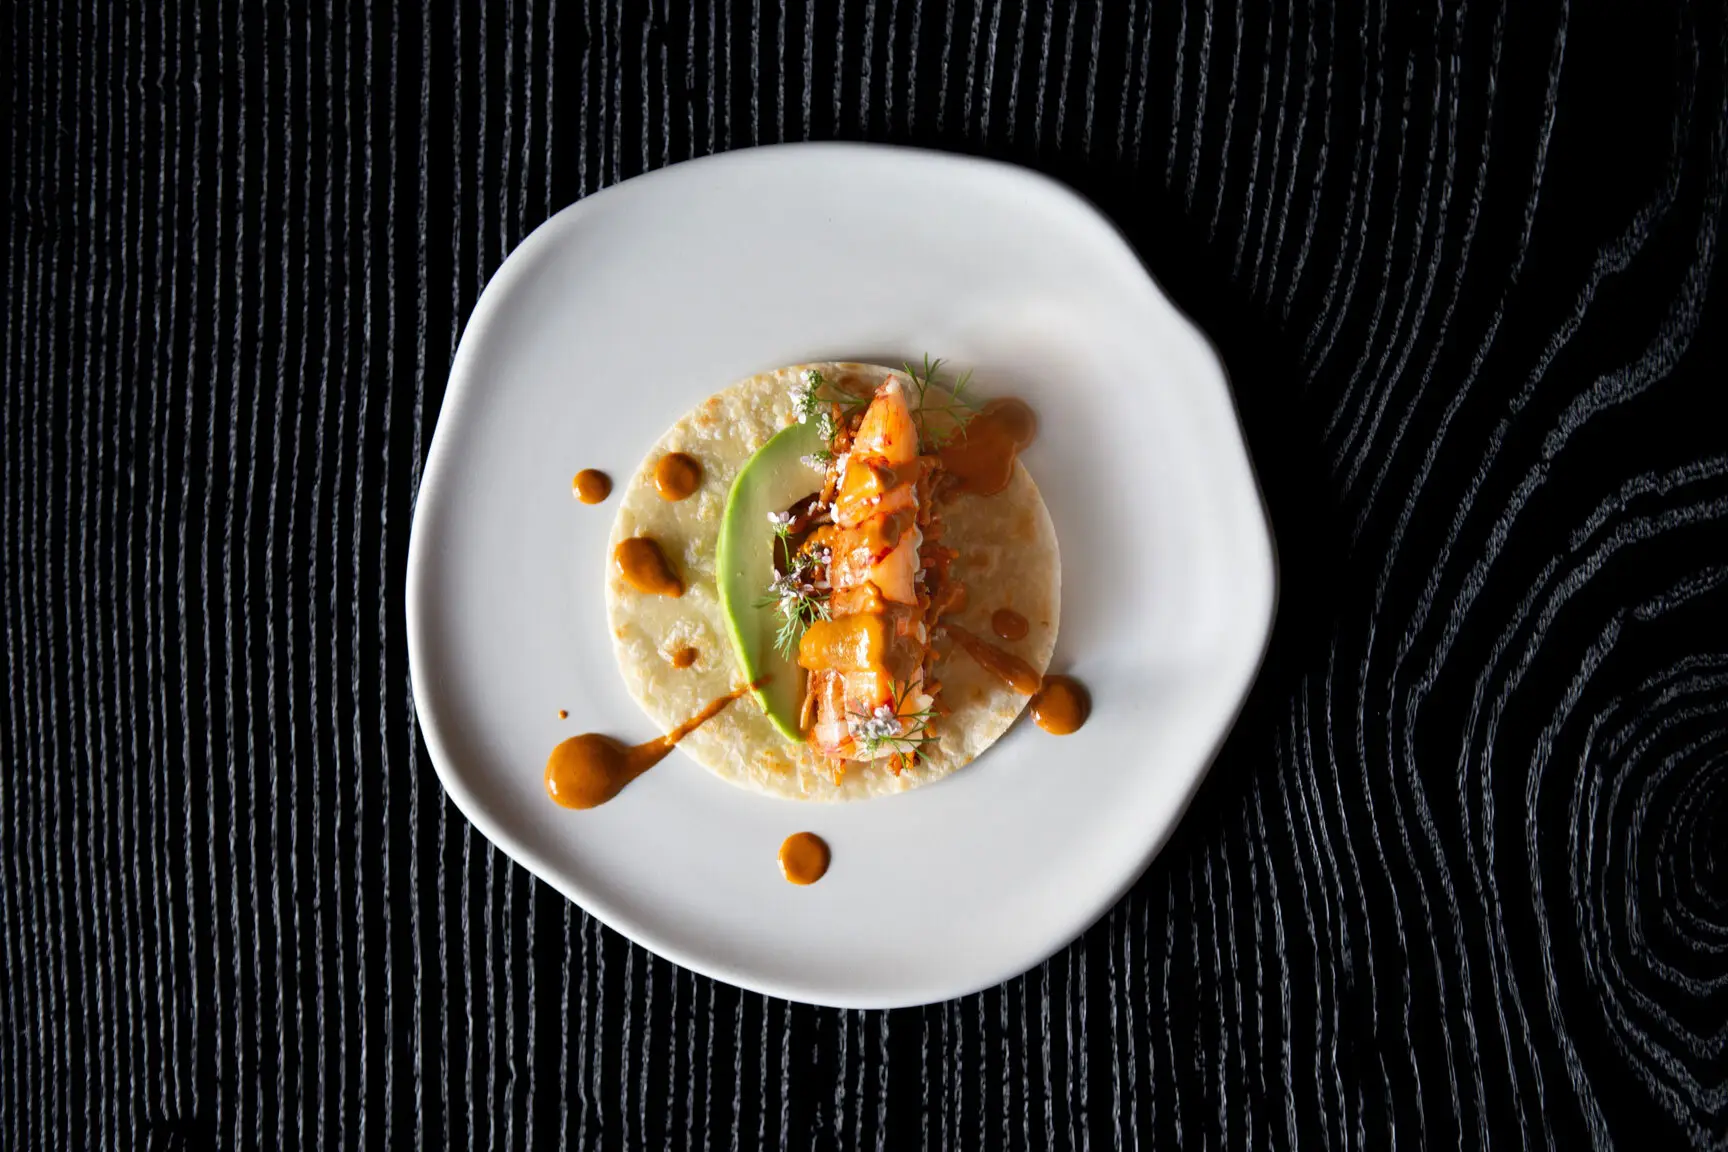
Lobster Taco: Flour sourdough tortilla with lobster shell bisque and local red spiny lobster
Valle
222 North Pacific Street, Oceanside, California 92054 866-723-8906 | valleoceanside.com